VA → Home Loans for Veterans & Military Families
VA home loan guidance for eligible veterans, active-duty service members and military families, with deep roots in Tucson and Southern Arizona.


Zero Down Financing for Veterans & Military Families
Eligible veterans, active-duty service members and certain surviving spouses may be able to purchase a qualifying primary residence with 0% down and no monthly private mortgage insurance.
VA financing can also go beyond buying an existing home, with potential options for refinancing, construction, renovation and accessing home equity, depending on eligibility and available programs.
Whether you're buying, relocating to Southern Arizona, preparing for a PCS, or evaluating your current mortgage, The Polder Group can help you understand your options and determine your next step.
Trusted by thousands of Tucson and Southern Arizona homebuyers
4,500+ Five-Star Reviews | 1,200+ Google Reviews | 3,300+ Experience.com Reviews
A Personal Connection to Tucson's Military Community
For Derrick Polder, the connection to Tucson's military community started long before he entered the mortgage business.
Derrick was born into a military family on a military base in Athens, Greece, and grew up in Tucson with his family at Davis-Monthan Air Force Base.
Years later, that connection came full circle when Derrick was selected as an Honorary Commander with the Desert Lightning Team at Davis-Monthan AFB.
Today, Derrick and The Polder Group help veterans, active-duty service members and military families understand their VA financing options and navigate the mortgage process from pre-approval through closing.
Our goal is simple: help you understand how to make the most of the VA home loan benefit you've earned.
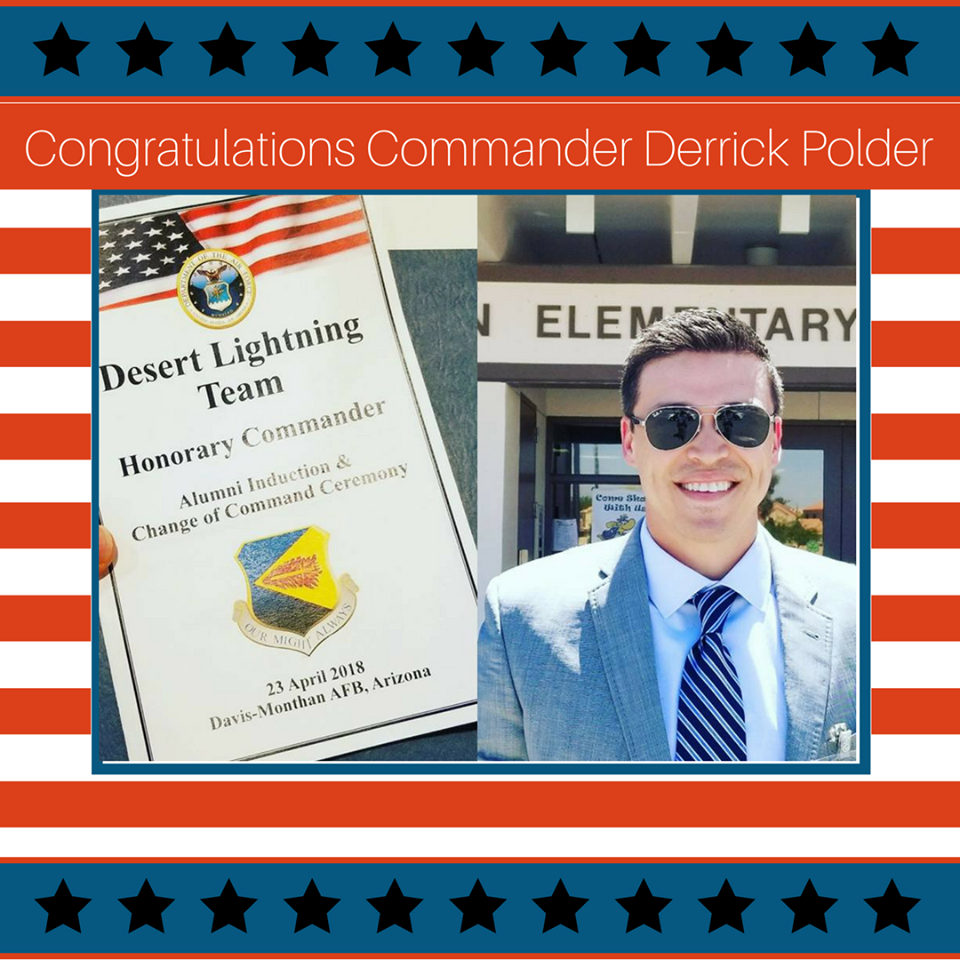
Derrick Polder at Davis-Monthan Air Force Base following his Honorary Commander recognition with the Desert Lightning Team in 2018.
Quick Answer: What is a VA loan?
A VA home loan is a mortgage option available to eligible veterans, active-duty service members and certain surviving spouses. VA loans are made by private lenders and backed by the U.S. Department of Veterans Affairs.
For eligible borrowers, that can provide powerful home financing advantages.
VA home loans offer benefits like:
- 0% down may be available
- No monthly private mortgage insurance
- Limits on certain borrower-paid closing costs
- No prepayment penalty
- VA eligibility may be reusable
- Purchase and refinance options
Your VA benefit may also provide options beyond purchasing an existing home, depending on your eligibility and available loan programs.
What Do You Want to Do With Your VA Benefit?
VA financing isn't limited to one type of borrower or one type of transaction. Start with what you're trying to accomplish.
Buy a Home
Eligible VA borrowers may be able to purchase a qualifying primary residence with 0% down and no monthly private mortgage insurance.
Refinance an Existing VA Loan
Already have a VA-backed mortgage? A VA Interest Rate Reduction Refinance Loan (IRRRL), commonly called a VA Streamline Refinance, may provide a refinancing option for eligible borrowers.
Access Home Equity
A VA cash-out refinance may allow eligible homeowners to refinance their mortgage while accessing available home equity.
Build a Home
Eligible borrowers may have VA construction financing options, including qualifying One-Time-Close construction financing.
Renovate a Home
VA renovation financing may provide eligible borrowers with an option to finance a qualifying home along with eligible repairs or improvements.
Buying Near Davis-Monthan Air Force Base?
If you're relocating to Tucson because of a PCS, your home search may begin before you ever arrive in Arizona.
That can create questions beyond simply finding a mortgage:
- When should I get pre-approved?
- Can I begin the homebuying process before I arrive in Tucson?
- How should I think about my housing budget?
- What happens if my PCS timeline and closing date don't line up?
- What should I know about the VA appraisal process?
- Where should I start looking around Davis-Monthan?
The Polder Group can help you understand the financing side of those decisions while you prepare for your move.
Exploring Communities Around Davis-Monthan?
Military families relocating to the Tucson area often research communities including Rita Ranch, Vail, East Tucson, Sahuarita and Greater Tucson.
Your ideal location depends on much more than distance from the base. Home prices, commute, schools, property type, lifestyle and long-term plans can all affect the decision.
VA Loans Explained by Derrick Polder
Sometimes it's easier to hear the explanation than read another mortgage page. Watch Derrick explain important VA home loan benefits, eligibility considerations and what veterans and military families should understand before buying.
Who Qualifies For A VA Loan?
You may be eligible if you are a qualifying:
- Veteran
- Active-duty service member
- National Guard member
- Reservist
- Eligible surviving spouse
What Is a Certificate of Eligibility?
A Certificate of Eligibility (COE) helps verify that you meet applicable VA service requirements.
Don't have your COE yet? That's okay.
You don't need to have every part of the VA process figured out before talking with us.
What Credit Score Do You Need for a VA Loan?
The VA does not establish one universal minimum credit score for VA-backed home loans. Individual lenders may establish their own credit and underwriting requirements.
Your credit score is also only one part of your overall mortgage profile. A lender may consider factors including your income, debts, employment, credit history, assets, residual income and the property being financed.
Concerned About Your Credit?
Don't automatically disqualify yourself based on a number you saw online. Talk with us about your actual situation.
Income and Debt
- Stable income and employment history are important
- VA loans use residual income guidelines to help determine affordability
- Debt-to-income ratios are often flexible depending on the full financial picture
Property Requirements
- The home must be your primary residence
- Properties must meet VA minimum property standards
- Eligible properties may include single-family homes, approved condos, and some multi-unit properties
VA Funding Fee
Most VA borrowers pay a one-time VA funding fee that helps support the VA home loan program. Depending on your eligibility and the type of VA loan, the amount may vary or you may qualify for an exemption.
The funding fee can often be financed into the loan, rather than paid entirely out of pocket.
- Amount varies based on the type of VA loan and other applicable factors
- Previous use of your VA benefit may affect the funding fee
- Some eligible borrowers may be exempt
- The funding fee can often be financed into the loan
Not sure what applies to you? We can help you understand how the VA funding fee may affect your specific loan scenario.
Common VA Loan Myths
There's a lot of misinformation about VA home loans. Here are some of the most common myths we hear from veterans and active-duty military members in Tucson and Southern Arizona.
❌ Myth: You need perfect credit to qualify.
✅ Fact: The VA does not establish one universal minimum credit score for VA-backed home loans. Individual lenders may establish their own credit and underwriting requirements.
❌ Myth: VA loans take longer to close.
✅ Fact: A VA loan does not automatically mean a longer closing. Timing depends on factors including the property, appraisal, documentation, underwriting and the individual transaction.
❌ Myth: VA loans are only for first-time homebuyers.
✅ Fact: VA home loan eligibility is not limited to first-time buyers. Eligible borrowers may be able to use their VA benefit more than once.
❌ Myth: You have to make a down payment.
✅ Fact: Eligible borrowers may be able to purchase a qualifying home with 0% down, subject to VA and lender requirement
❌ Myth: VA loans require monthly mortgage insurance.
✅ Fact: VA loans do not require monthly private mortgage insurance, which is one of the program's major benefits for eligible borrowers.
VA Appraisal vs. Home Inspection: What's the Difference?
A VA appraisal and a home inspection are not the same thing. Understanding the difference can help you know what to expect when buying a home with VA financing.
VA Appraisal
A VA-approved appraiser provides an opinion of the property's value and evaluates the home for applicable VA Minimum Property Requirements.
Home Inspection
A separate home inspection provides a more detailed evaluation of the home's condition and may identify issues that aren't the primary purpose of a VA appraisal.
A VA appraisal doesn't mean the home has to be perfect. If a property condition is identified, what happens next depends on the issue and the individual transaction.
VA Loan vs Conventional Loan
| Feature | VA Loan | Conventional Loan |
|---|---|---|
| Down Payment | 0% down for eligible buyers | Typically 3%–5% minimum |
| Mortgage Insurance | None required | Required under 20% down |
| Credit Flexibility | More flexible | Typically stricter |
| Closing Costs | Limited and regulated | Varies by lender |
| Eligibility | Military only | Open to all qualified buyers |
⭐⭐⭐⭐⭐
"Tony and Stormi did a terrific job facilitating my mortgage. I highly recommend CrossCountry, especially if you are a Veteran!"
— Myles F. Verified Google Review
For many eligible Tucson and Southern Arizona veterans, VA financing can provide lower upfront costs and greater purchasing power than conventional loan options.
Whether an FHA loan is the right fit or not, The Polder Group will help you compare all your options. Explore our Mortgage Loan Programs in Tucson & Southern Arizona, learn more about Buying a Home in Tucson, or review Mortgage Refinance Options in Southern Arizona if you already own a home.
FAQs.
-
Who qualifies for a VA loan?
VA loans are available to eligible veterans, active-duty service members, and certain members of the National Guard and Reserves, as well as some surviving spouses.
-
Do VA loans require a down payment?
No. Most VA loans offer 100% financing, meaning no down payment is required.
-
What is the VA funding fee?
The VA funding fee is a one-time fee that helps support the program. It can often be rolled into the loan amount.
-
Do VA loans require mortgage insurance?
No. VA loans do not require monthly mortgage insurance.
-
Can I use a VA loan more than once?
Yes. VA loans are reusable depending on your remaining entitlement.
-
Can I buy an investment property with a VA loan?
No. VA loans are for primary residences only.
-
How long does it take to close a VA loan?
Most VA loans close in about 30 to 45 days depending on the transaction.
-
What credit score is needed for a VA loan?
Many lenders look for scores around 580 to 620, though guidelines are flexible.
-
Do I have to be stationed in Tucson to use a VA loan?
No. You can use your VA loan benefit anywhere, including relocating to Tucson or Southern Arizona.
-
Can I buy near Davis Monthan Air Force Base with a VA loan?
Yes. Many eligible buyers use VA loans to purchase homes near the base and throughout Tucson.
- Typically 580–620 (varies by lender)
- 0% down available
- Primary residence only
- No monthly mortgage insurance
- VA funding fee may apply (can be financed)
- Flexible credit and income guidelines
- Must meet VA eligibility requirements (Certificate of Eligibility)
Terms and conditions may apply. Programs can change at any time and must meet all eligibility guidelines. All credit offers are subject to approval. The Polder Group is not affiliated with any government agency. Program availability may require specific training or licensing where applicable.


- Over 4,500 Five-Star Reviews
- 1,200+ Google Reviews
- 3,300+ Experience.com Reviews